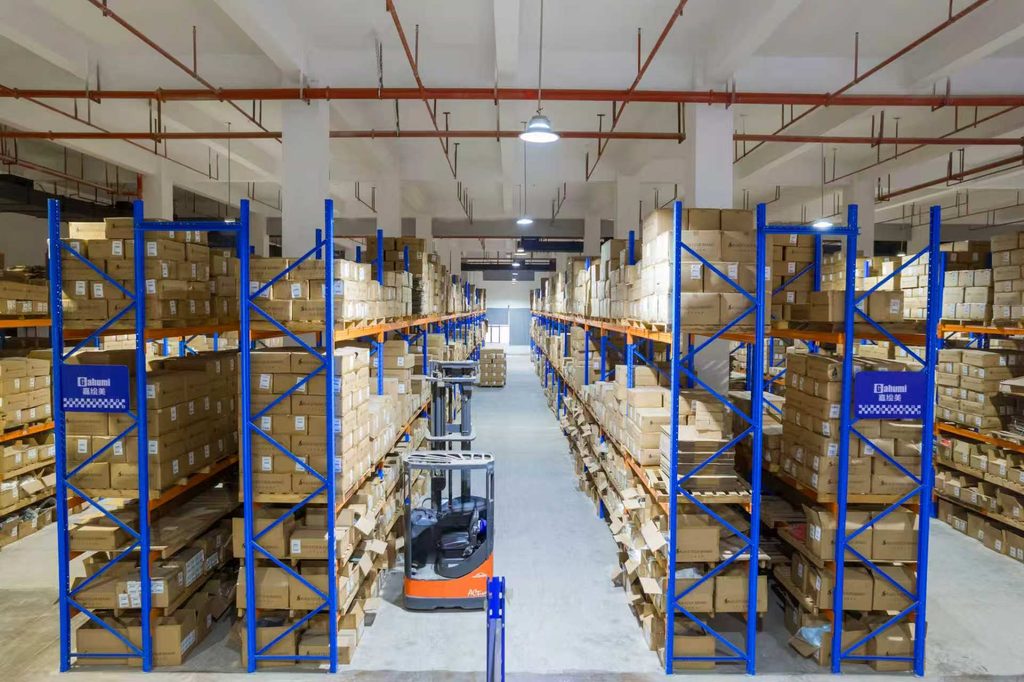
Twenty totes arrive at a shop. That event may be a completed wholesale delivery, or it may place somebody else’s stock in the shop’s custody under an agreed consignment arrangement. The same physical count can belong to very different commercial records.
A cotton tote bag consignment handover needs a shared stock record before anybody interprets delivery as a sale. This guide concerns a brand or distributor discussing third-party retail custody and reporting. It is not a Gahumi consignment offer, contract template or conclusion about ownership, insurance, tax or payment rights.
Agree the commercial terms first
Have the actual parties and their qualified advisers establish the proposed terms, responsibilities and applicable requirements. Identify who owns the goods at each stage, who may sell or discount them, how loss or damage is handled, and which event affects payment. Do not infer those answers from the word “consignment”.
SAP’s customer-consignment workflow distinguishes stock initially placed with the customer from a later reported issue and from returned stock. It is a software-process example, not a legal model for every retail agreement. Use the actual accepted arrangement to define the records your teams need.
Count the stock received into custody
List the product reference, design, quantity and condition transferred to the shop. Record the sending party, receiving location and date, together with the acknowledgement needed under the agreed process. A generic note saying “twenty bags” will not distinguish two similar prints.
Separate saleable units, the handling sample and anything held for review. If an opening-count difference exists, reconcile it before building later sales reports on that balance. Use the delivery discrepancy record for the evidence, rather than treating missing stock as sold stock.
Keep a shop handling sample separate from untouched saleable stock in a cotton or cotton canvas range intended for repeated customer use. Check the fabric, print and handles when stock is returned; do not assume an unused-looking bag is unchanged. An undated design can be considered if the brand wants stock to remain relevant beyond a short campaign, subject to the artwork permission and actual condition.
Decide how the shop’s system will keep this stock distinguishable from stock it has bought outright. A physical shelf divider alone may not distinguish the ownership or settlement treatment in the reporting system. Ask the responsible stock and finance teams to confirm their method.
Record sales, returns and transfers separately
Use separate entries for additional receipts, reported sales or agreed issues, customer returns, transfers, damaged units and stock sent back to the supplying party. Name the product version and supporting reference for every change.
A return from a consumer after a recorded sale is not the same event as sending unsold stock back to its owner. Which records and financial adjustments follow each event must be confirmed by the parties. Do not erase the original movement just to make the closing balance look tidy.
Name the person who can authorise a shop-to-shop transfer before any stock moves. The receiving location needs its own opening balance, and both records must identify the same transfer. A bag leaving one shop has not necessarily been sold to a customer.
An illustrative reconciliation
Suppose a location begins with 20 saleable units, receives 10 more, reports 8 sold and returns 5 unsold units to the supplying party. With no other movements, the expected closing custody stock is 17 units: 20 + 10 − 8 − 5.
This is arithmetic only, not a real customer example or a settlement rule. Count the physical stock and investigate any difference. It does not establish what amount is payable, whether a report has been accepted or how tax should be handled.
The retail assortment trial guide asks which designs justify a future buying decision. This record answers a different question: what third-party stock is held, what happened to it and what information must be presented for the agreed reconciliation.
Agree how the arrangement will end
Agree the closing steps alongside the commercial terms: final reporting date, physical count, return authorisation, condition review and acknowledgement of what was received back. Keep any disputed quantities visible rather than treating the entire file as settled.
Give the authorised finance team the accepted movement record and the supporting documents it requests. Mark a submitted report, an approved reconciliation and a completed payment separately. None is automatically established by a stock spreadsheet total.
A supplier manufacturing a new range needs the brand’s authorised buying quantity, not an assumed downstream consignment forecast. Ask Gahumi about a normal production quotation with the specified bag, artwork, quantity and destination. Any separate brand-to-retailer consignment arrangement remains for those parties to establish.
Request a production quote for your range Discuss your tote range
Send product requirements to gzgahumibag@gmail.com, without customer payment or personal records.